


Construction Loan Management, Built for Credit Unions
Run draws, coordinate inspections, and keep an exam-ready record in one place, so your team can say yes to the construction projects your members bring you.
Bring a project your members have asked about, and a Built specialist will walk through a live draw, an inspection, and an exam-ready portfolio report.
Lender clients
In active real estate finance
Median draw turnaround, submission to funding, last 12 months
What Is Construction Loan Software for Credit Unions?
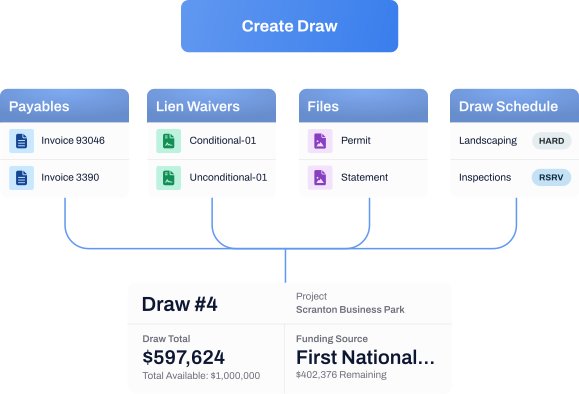
Construction loan software manages a construction loan after it closes, when funds release in stages against a budget and completed work. It covers draw requests, inspections, risk checks, and funding.
Built is a construction lending partner for credit unions. It centralizes the lender, borrower, builder, and inspector in one system.
Say Yes to the Member in Front of You
A member brings you a construction project that fits your credit union well. You want to help. The open question is whether your back office is ready for draws, inspections, and exam requests.
$187.1B
Commercial loans secured by real estate at federally insured credit unions, as of June 30, 2026.
Source: NCUA Quarterly Credit Union Data Summary, Q2 2026
+10.0%
over the year
Most credit union construction lending starts on email, spreadsheets, and the knowledge of one or two people. That works for the first loan. It gets harder with every new project and every exam.
In conversations with credit unions, three concerns come up:

Members ask about construction loans, and no one wants to turn them away.

Few teams want to build a construction lending department to get there.

Other credit unions are growing their construction portfolios, and no one wants to be left behind.
Inspections You Can Trust, Including Outside Your Home Market
NCUA’s rule for construction and development lending (12 CFR 723.6) allows funds to be released only after on-site inspections, documented in writing. For many credit unions, the hard part is finding inspectors they trust, especially on a project outside their home market.
Built Marketplace gives your team a vetted network instead of an inspector search. 368 inspection firms fulfilled Marketplace orders in the past year, and more than 300 lending institutions have used it.
Inspections ordered through Marketplace come back 30% faster at the median than inspections ordered outside it, 7 in 10 are completed within three days of order, and half as many take five days or more. Each report attaches to the draw, so the record stays auditable.
Also available:
Plan and Cost Review
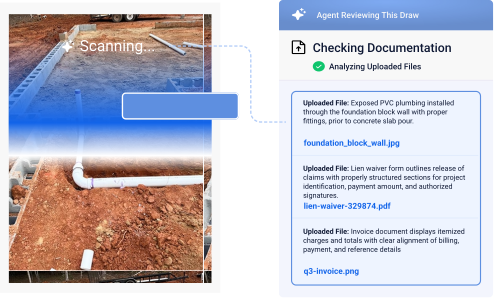
Snapshot + AI photo inspections
99% accurate, with 90% less inspection time
What Built Gives Your Lending Team

AI Draw Agent
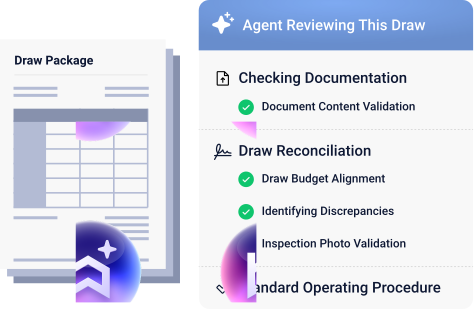
Reviews each draw against your own policies and flags discrepancies automatically.
~9 min
to process a draw at the median
2x
more risks flagged than manual review

Central Draw Desk
One queue for every incoming draw, with configurable approvals, document requirements, and automated chasing for missing items.

Portfolio Reporting and Risk
Real-time budget tracking and exposure by borrower, geography, and property type, with stale-project alerts.

Member and Builder Portal
Members and builders submit requests, upload documents, and track status without calling the branch.
Credit Unions Already Run on Built
Credit union peers have already made this move. Truliant Federal Credit Union, United Federal Credit Union, and Altra Federal Credit Union each moved from manual spreadsheet processes to a centralized platform.

Aug 21, 2026
9 min
United Federal Credit Union
Draw turnaround cut in half across 194,000 members in 7 states.

Aug 21, 2026
9 min
Altra Federal Credit Union
80% of draws now arrive through the platform.

Ready to take on more construction projects?
Works With Your Core and LOS
Built acts as the front door to your core. It connects to the core banking and loan origination systems credit unions already run, including Encompass, nCino, FIS, and Fiserv, and pushes clean, approved data downstream without replacing your core. Your core keeps running accounts and the general ledger, and the construction work happens in one connected place.
If your mortgage or consumer lending team already works on one of these systems, construction lending is an extension of an operation they know, not a new one to build from scratch.

Built for Safety
A well-documented construction loan includes a budget review before closing, an approved disbursement process, on-site inspections, and confirmation of no intervening liens. Built keeps each of those steps in the draw record.
Security your vendor review will ask about
Independently audited controls, documented for your third-party due diligence.


Frequently Asked Questions
What does NCUA require before releasing construction loan funds?
What does NCUA require before releasing construction loan funds?
NCUA’s construction and development rule (12 CFR 723.6) requires on-site inspections, documented in writing, before funds are released. NCUA’s examiner guidance also expects disbursement controls that protect against misuse of loan proceeds and intervening liens. In Built, inspection orders are created from the draw, and inspection results are checked against the draw request before approval.
Can we set approval limits that match our credit union's lending authority?
Can we set approval limits that match our credit union's lending authority?
Yes. Built ties approval authority to dollar amounts and routes draws to approver groups, so each draw goes to the people your board-approved policy names. Overrides are recorded in the audit trail.
How does Built fit into our third-party vendor due diligence?
How does Built fit into our third-party vendor due diligence?
NCUA Supervisory Letter 07-01 organizes vendor due diligence around risk assessment, due diligence, and ongoing monitoring. Built provides the independently audited control reports listed above for your review. Your credit union keeps approval authority on every draw.
Can credit unions use Built for SBA 7(a) and 504 construction loans?
Can credit unions use Built for SBA 7(a) and 504 construction loans?
Yes. SBA construction draws run through the same draw desk, inspection ordering, and approval workflow as your other construction loans, so the documentation SBA expects stays with each draw. See how lender-managed SBA construction draws work in Built.
Do SBA-guaranteed construction loans count toward our member business lending limit?
Do SBA-guaranteed construction loans count toward our member business lending limit?
Partly. Under 12 CFR 723.8, a loan that a federal agency fully guarantees is excluded from the aggregate limit. For a partially guaranteed loan, such as an SBA 7(a) loan, the guaranteed portion is subtracted from your net member business loan balance, and the unguaranteed portion counts.
See Built for Your Credit Union
See how Built manages construction draws end to end, and what it would look like for your portfolio.